School Finance 101 FAQ
How are Texas public schools funded?
The State determines the total amount a district is allowed to receive per student each year. This is known as the “Basic Allotment" - The amount the state allocates per student. We can also think of this as the size of a district’s cup.
The size of the district’s cup represents the total amount the state allocates the district to receive “Basic Allotment”.
The cup is first filled with the local share (locally generated property tax revenue), and then the state fills any remaining portion of the allowable cup size with state revenue.
If property tax revenue increases (local share), the state reduces its share to keep the district at the set cup size.
In simple terms: The state sets the size of the cup. Local property taxes fill the cup first, and the state fills what is left.
If the local share overflows the allowable cup size, the state does not add to it but does take any overflow and reallocates it to other districts (recapture) or holds on to it as general revenue.
Who sets the school tax rate?
Within the overall school property tax rate, there are two separate tax rates - M&O (Maintenance & Operations) and I&S (Interest & Sinking).
- A district’s M&O (Maintenance & Operations) tax rate correlates to the district’s M&O budget.
This tax rate and budget funds everything associated with day-to-day operations. Such as staff salaries, student academic and extracurricular programs, supplies, student services, safety and security, special programs, facilities maintenance and repair, utilities, insurance, transportation, and fuel - etc.
The State of Texas sets the M&O tax rate for Texas School Districts, and issues a Maintenance and Operations MCR (maximum allowable compressed tax rate) each year that Texas school districts are not allowed to exceed (unless authorized through a disaster penny adoption or VATRE - Voter Approval Tax Rate Election).
In addition, districts that set tax rates below the State MCR are required to pay the state any difference in revenue that would have been generated by the higher MCR.
- A district’s I&S (Interest & Sinking) tax rate correlates to the district’s I&S budget.
This tax rate and budget pays debt on bonds for items such as construction, renovation, land, etc.
Texas school districts are responsible for adjusting the I&S (Interest & Sinking) rate to a level that allows the
district to maintain its bonded debt repayment obligations - this is referred to as the “rate to maintain”. Districts may not
set I&S tax rates higher than a rate to maintain current bonded debt obligations unless a board and state approved
plan is in place on how the district will use the funds generated (beyond what is needed to maintain debt obligations)
to defease/pay down other debt a district may have.
I’ve noticed property tax costs have increased. Has the school tax rate gone up?
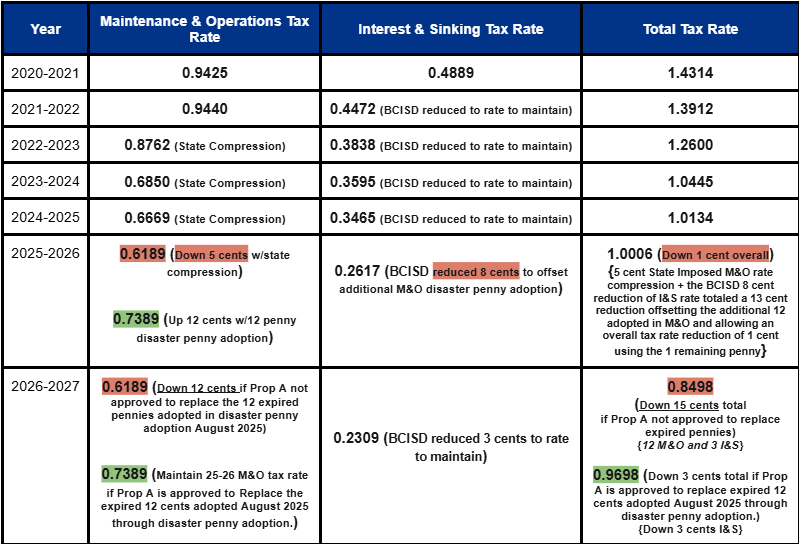
No, the overall school district tax rate has not increased. Due to state imposed compression of the M&O (Maintenance & Operations) school tax rate, the overall school tax rate has decreased from 1.4314 in 2020 down to 0.9698 in 2026.
If the school tax rate has decreased from 1.4314 in 2020 down to 0.9698 in 2026, why are property tax costs increasing?
Property tax costs may have risen as a result of increases in property appraisal values or property taxes levied by other entities.
Who determines property values in the district?
The County Appraisal District sets property values - not the district.If more revenue is being generated through higher property values, why is the school district asking for more money?
The size of the district’s cup represents the total amount the state allocates a district to receive (Basic Allotment).
If an increase in property values cause additional revenue to be generated above the allowable basic allotment (overflows the allowable cup size), the state takes the overflow and reallocates it to other districts (recapture).
The allowable cup size (Basic Allotment) of $6,160 per student remained the same from 2019-2025, and increased by $55 to $6,215 in 2025-2026. However, inflation over that period of time increased the actual cost to educate each student by an additional $1,300. This funding gap resulted in a $4.3 million loss for BCISD in 2025-2026, and a combined loss of $15.7 million since 2019.
In addition, Bay City ISD enrollment has declined by 385 students over the past six years, consistent with the statewide declining enrollment trend; representing a $2.3 million reduction in revenue. Together with the $15.7 million gap between the basic allotment and inflation, these factors represent a cumulative $18 million loss since 2020.
Since the amount of M&O revenue a district is entitled to receive is determined by the size of its funding “cup”, increasing local property values alone does not increase the size of that cup. However, a VATRE can add additional Tier II funding, effectively expanding the district’s overall funding entitlement and ultimately increase its cup size.
How do tax abatements for business and industry affect the school district?
Unlike cities and counties, school districts cannot grant tax abatements under Chapter 312. Under former Chapter 313 law, however, school districts could participate in state-authorized value limitation agreements with large industrial projects. These agreements often generated supplemental revenue for the district while preserving state funding under Texas school finance formulas. In many cases, Chapter 313 projects created additional revenue opportunities for school districts that would not have otherwise existed.
Local homeowners do not pay more because a company is operating under a Chapter 313 value limitation agreement and the school district does not receive less funding. Public Schools are funded primarily through the state’s school finance formulas based on student attendance, and any funding impact associated with the limitation is borne by the state rather than local tax payers.
Chapter 313 limitations only affected the M&O portion of a school's tax rate. Industrial facilities operating under these agreements still paid the full I&S tax rate on 100% of their property value. By moving eligible debt from M&O to I&S, the district can collect taxes on the full value of these industrial properties. Based on current property values, each penny levied on the I&S side generates approximately $92,000 more in revenue than a penny levied on the M&O side; thereby lessening the local residential tax burden in paying for bonded debt in the I&S budget.
Unfortunately, the Chapter 313 program is no longer available to school districts. In its place, the State of Texas created the JETI (Jobs, Energy, Technology, and Innovation) program. Existing 313 agreements remain in effect through their original terms, but districts are no longer authorized to enter into new Chapter 313 value limitations.
If Prop A is passed by voters in the November 3, 2026 election and the district is authorized to keep/replace the 12 Maintenance & Operations disaster pennies they adopted in August 2025, is the district able to come back at a later date and ask for an additional Maintenance & Operations tax rate increase?
Prop A would authorize BCISD to replace the 12 disaster pennies adopted in August 2025. The state does not allow a district to adopt more than the 12 additional pennies through either a disaster penny adoption or a Voter Approval Tax Rate Election.
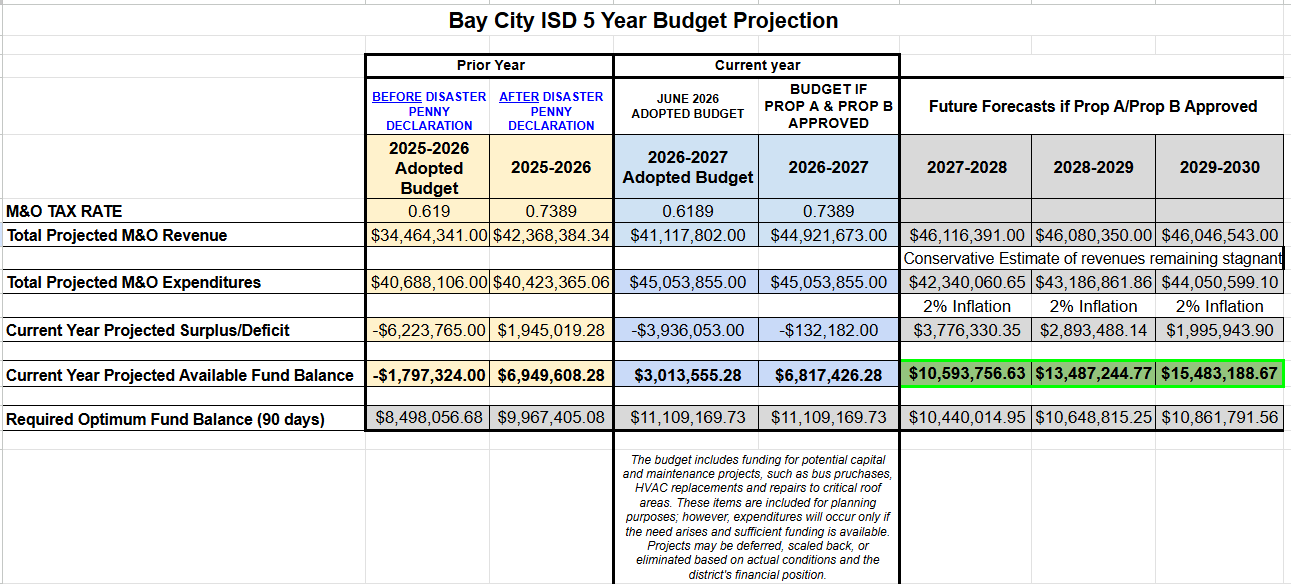
“It appears that the financial impact of Prop A&B would only allow the district to break even when taking projected deficit budgets into account. Are Props A&B a temporary solution? Does the M&O (Maintenance & Operations) fund balance continue to decrease? Does the deficit budget return?”
The 12 disaster pennies adopted in August 2026 was the short-term temporary solution to secure the District's financial position for the 2025-2026 school year. Based on the input from multiple experts in the field of Public School Finance and the work and input of the 52 member BCISD Strategic Planning Committee, the recurring recommendation for the district to achieve long term financial stability is to maintain the $3.6 M of increased revenue provided through the 12 penny August 2025 Disaster Penny Adoption, and remove existing debt from the Maintenance and Operations budget.
Prop A, if approved by voters, would authorize replacement of the 12 Disaster Pennies that expired in July 2026, providing the estimated $3.6 M in additional revenue beyond the State's basic allotment allowance each year moving forward.
Prop B, if approved by voters, would authorize the purchase of bonds to pay for existing loans and notes paid for out of the Maintenance and Operations budget and allows the bonds to be paid using the I&S budget and tax rate.
Each penny on the I&S side is worth $92K more than the M&O side based on current property values, and business and industry carry a 77% share of paying district bonded debt in the I&S budget - thereby lessening the local residential tax burden by paying for bonded debt in the I&S budget.
If Prop A and Prop B are approved – Current financial projections show that BCISD can attain a balanced budget as well as a fund balance above state required optimum levels beginning with next year’s 2027-2028 budget, and projected continued fund balance growth in subsequent years.